Conservation Easement Attorney
Last updated on November 10, 2026
Key Takeaways
- The 2026 shift to individual assessments: The IRS stopped focusing only on large court battles with partnerships. They are now sending tax bills directly to individual investors.
- Strict 6-month window: Opening an IRS notice starts a hard six-month clock to file an appeal or request a refund. Waiting for a final collection letter destroys your legal leverage.
- Why partnership defenses fail: Partnerships usually lose in tax court because they only argue over land value. Your real chance to win comes at the individual level, where procedural defenses are much stronger.
- The 4-pillar advantage: Standard CPAs and general lawyers miss key defenses. They lack deep skill across partnership tax, IRS appeal procedures, individual tax rules and conservation easement law.
- Why Bomar Law Firm stands out: Led by former IRS Chief Counsel attorney Cal Bomar, we only represent individual investors – never deal promoters. We audit for illegal interest charges, challenge bad extension forms and fight for tax penalty waivers.
- Protect your assets before deadlines pass: Call Bomar Law Firm today at 404-841-6561 for a private strategy session with former IRS counsel.

Cal Bomar is a former IRS Chief Counsel attorney who is competent in IRS and state tax cases involving syndicated conservation easements. Our team includes some of the best-known tax lawyers in the U.S. While most law firms that handle these cases represent promoters, our firm only represents investors in easement deals. We are focused on getting investors the most favorable relief. We understand how stressful an IRS tax case can be and know that conservation easement investors find themselves in this situation through no fault of their own. It is important to address the problem so that you can get a positive result and put it behind you.
For more information on conservation easements, check out our conservation easements frequently asked questions page.
Table of Contents
Here’s What You’ll Get From Bomar Law Firm:
- A free consultation and strategy session with a former IRS attorney.
- The vast experience and resources of our best tax lawyers in Atlanta.
- Attorneys who you can reach and receive an update from the same day.
- Attorneys and staff who care about you and your case and who will fight tirelessly to get you the most favorable result.
Why Is The IRS Attacking Syndicated Conservation Easement Deals?
To create a syndicated conservation easement, a promoter brings together a group of investors, places them into a passthrough entity (like an LLC that is a partnership for tax purposes) that has purchased land, and then places a conservation easement on that land, restricting the private use of the property in order to protect its conservation value. The partnership takes a charitable deduction for the reduction in the value of the land and passes that tax deduction to the investors on Form K-1.
Conservation easements are legal when set up correctly and using the actual value of the property. In fact, easements were often marketed to investors as a way to help the environment in a way that was legal and even encouraged by Congress. Most promoters told investors that they used very conservative appraisals, using two appraisers and taking the lower of the two appraisals. Investors were often advised by an attorney and a CPA that the transaction was legal. In addition to the appraisals, many were also shown opinion letters from law firms stating that the transactions were done legally.
IRS asserts that most syndicated conservation easement transactions are abusive. IRS points to examples of promoters who appraised the land at extreme multiples over its recent purchase price. IRS also seeks to disallow deductions using technical defects, such as asserting that the deed of conservation did not meet the requirements because it did not convey the property in “perpetuity” (forever). The IRS has indicated that it may also challenge the transactions based on the partnership anti-abuse rule, economic substance and other rules or doctrines. The IRS asserts that the easements have resulted in the Treasury losing over 20 billion dollars to fake charitable deductions since 2010.
The 2026 Shift To Individual Assessments And The Six-Month Window
The IRS is no longer fighting conservation easement cases in sweeping, partnership-level litigation battles. As of 2026, the IRS has unleashed a massive wave of individual tax assessments issued directly to investors. If you open your mail to find an individual assessment letter, a ticking clock begins immediately.
- The strict six-month deadline: From the exact date stamped on your individual assessment letter, you have a hard six-month window to pay the assessment and file a formal request for a refund, or file a defensive appeal.
- The danger of waiting: Waiting for a formal lien or levy notice to arrive before taking action is dangerous. While our team can still execute defensive alternatives for a lien or levy, letting your six-month window close will strip you of much-needed leverage.
- The full-pay trap: If you let the six-month window pass and simply full-pay the balance without a comprehensive strategy in place, you forfeit your right to fight the accrued interest and penalties.
At our firm, we do not protect the promoters who sold these deals, and we do not represent the partnerships. We strictly protect individual investors. If you have received an IRS notice, time is your greatest enemy, but procedural IRS errors may be your greatest asset.
Tracking The Evolution Of IRS Conservation Easement Enforcement
What follows is a general timeline of conservation easement enforcement and the IRS:
- 2023 – Legislative bans and document swarms:
- The IRS announces audits of all conservation easement deals not beyond the statute of limitations.
- The DOJ investigates promoters who took extreme valuation multiples and who falsified documents.
- Congress passes a law to disallow future syndicated conservation easement deals over 2 ½ times the taxpayer’s basis.
- Many cases proceed to trial, with the court imposing penalties at the partnership level.
- 2024 – The IRS settlement initiative:
- The IRS Tax Court’s tax docket balloons significantly.
- To reduce the docket, the IRS sends settlement offer letters with more favorable terms for nondocketed cases.
- Under the new initiative, the penalty for gross valuation misstatements for undocketed cases is 5% and the tax rate at the partnership level is 21%.
- 2026 – Individual assessments and procedural deadlines:
- The IRS turns away from partnership-level litigation to mass-issued individual tax assessments.
- The IRS implements a six-month response window.
- The Kwong v. United States ruling becomes a crucial tool for investor relief.
- The IRS frequently misses its 12-month assessment deadline and other statutory rules.
Successful conservation easement defense requires thorough knowledge of the IRS’s tactics and how they have evolved over time. As leaders in conservation easement investor representation, our tax lawyers have successfully defended investors through every stage of federal and state clampdowns.
How We Defeat The IRS Using Its Own Rules
Land valuation metrics are only one tool to counter the IRS. In addition, we fight for our clients by taking advantage of the statutory regulations laid out by the IRS itself.
The IRS is required by law to issue individual assessments within a 12-month window after the overarching partnership case officially concludes. Because the IRS is completely overwhelmed by the sheer volume of conservation easement cases in 2026, they routinely miss their own deadlines. Our legal team meticulously audits every client’s timeline. If the IRS violates these strict statute-of-limitations windows, we can often use their own procedural violations to erase our clients’ tax liabilities entirely.
How Does The Kwong Interest Ruling Affect Conservation Easement Investors?
Kwong v. United States, also called the Kwong interest suspension ruling, is a major federal court case from 2025. It established that the IRS could not charge interest during a three-year suspension window during the COVID-19 pandemic. This window spanned from January 20, 2020, to July 10, 2023. However, the IRS continued to assess interest against conservation easement investors during this period. For more information on Kwong and the potential conflicts of interest you may encounter, check out our blog post ‘What Should You Know About the Kwong Interest Ruling?‘.
Beware Predatory Tax Firms With Conflicts Of Interest
In light of this ruling, some unethical law firms are collaborating with the promoters who originally peddled these unlawful, syndicated deals. Promoters send their investors to these predatory law firms, which then charge exorbitant contingency fees and extra hourly rates just to recover the Kwong interest refund. In exchange, the law firms advise their clients not to take legal action against the promoters. Investors should use discretion when hiring a tax defense law firm.
The Malpractice Trap: Why General CPAs And Standard Lawyers Fail
Defending a conservation easement assessment requires comprehensive knowledge at the exact intersection of four distinct areas of tax law:
- Partnership tax (Subchapter K): Deciphering complex pass-through adjustments, basis rules and Tier-1 partnership structures.
- IRS tax procedure and appeals: Tracking strict statutes of limitations, procedural deadlines and administrative relief protocols.
- Individual flow-through rules: Managing how partnership-level adjustments impact individual Form 1040 filings.
- Conservation easement law: Understanding federal land appraisal standards and statutory deed requirements.
When general tax professionals try to handle individual assessments without trial experience in all four pillars, they routinely miss deadlines and lose key procedural defenses.
“These conservation easement cases sit at the intersection where you have to both understand partnership tax – which even most tax attorneys don’t understand – plus you have to understand tax procedure, and then it flows through to individual income tax, and you have to know conservation easement law… It’s so many different specialties merging at one place that almost nobody understands them.”
— Cal Bomar, Former IRS Chief Counsel Attorney
Why Partnership Defenses Fail – And How Individual Defenses Win
“The partnerships have been losing because the only defense they have at trial is the valuation… They’ve marked up the valuation anywhere from 10x to as much as 200x what they paid for the land. They’re not going to win the valuation battle at tax court. But when it flows through on an individual assessment to the individual partner, that’s the first time I get to use individual partner-level defenses… Partner-level defenses are 100x stronger than the valuation defense.”
— Cal Bomar, Former IRS Chief Counsel Attorney
Fighting an IRS partnership audit feels like a losing battle because it centers on subjective appraisal numbers. Fortunately, when the IRS issues an assessment directly to you, the ground rules change. You can now use individual partner defenses that force the IRS to follow its own strict legal standards:
- Kwong Interest Relief: In Kwong v. United States, federal courts ruled that the IRS illegally charged interest during the COVID-19 pandemic pause (January 20, 2020 – July 10, 2023). Despite this ruling, the IRS still routinely charges this illegal interest. We automatically audit your tax transcripts to claim this money back under our standard flat fee.
- Defective Form 872 Extensions: To buy time, the IRS often asks taxpayers to sign extension agreements (Form 872). IRS agents frequently use flawed forms that leave out required legal wording, making those extensions completely invalid.
- 12-Month & 3-Year Statutory Deadline Errors: By law, the IRS must issue individual tax assessments within a strict 12-month window after an overarching partnership case officially ends. Because the IRS is overwhelmed with cases, agents often miss this deadline. When we spot this error, we can often wipe out your tax liability entirely.
By shifting the fight from subjective land appraisals to strict IRS procedural rules, individual partner defenses give you actionable leverage to stop enforcement, reduce liabilities, and resolve your tax case.
Strategic Guidance When Your Assessment Arrives
When an individual tax assessment arrives, your liquidity and goals determine the proper defense route:
- Pay and file a refund claim: Paying the tax balance or posting a cash deposit stops interest from growing. Submitting a formal Administrative Refund Claim within six months keeps your right to fight penalties, claim illegal interest back and raise IRS errors.
- Defense via collection due process appeal: If paying upfront is impossible, requesting a Collection Due Process (CDP) hearing after a lien or levy notice legally stops IRS collection efforts. This gives us time to arrange an affordable monthly payment plan or temporarily pause collections due to financial hardship.
Selecting the right strategy early prevents forced collection actions while keeping every procedural defense available.
Our Commitment Is To Investors, Never Promoters
At Bomar Law Firm, ethics and client loyalty come before everything else. We maintain an ironclad investor-only safeguard. We represent zero promoters and zero partnerships.
Many law firms handling these cases maintain quiet ties with the original deal promoters. They often charge high fees to recover small refunds while telling clients not to sue the promoters who sold them the unlawful deals. We have turned down millions in promoter fees to remain completely independent. We owe nothing to the promoters, so you have the absolute assurance that we will pursue every legal avenue to protect your personal assets and recover your financial losses.
Resolving IRS And Georgia State Tax Exposure
For Georgia residents, an IRS tax dispute automatically triggers a second tax issue with the Georgia Department of Revenue (GA DOR). Settling your federal case without fixing your state tax problem leaves you open to state tax liens, bank seizures and forced collection.
“For Georgia residents, this flows through and creates a state income tax problem as well… I’ve individually worked out relief with the state where they pay no penalties instead of 30%. Georgia only makes them, if they did five or six years of deals, pay back the last three under the voluntary disclosure program.”
— Cal Bomar, Former IRS Chief Counsel Attorney
Our legal team coordinates your federal and state tax cases together. By combining federal procedural defenses with the Georgia Voluntary Disclosure Program (VDP), we work to remove state penalties entirely and cap back-tax demands at just three years.
What To Expect When You Work With Us
At our firm, we have removed all barriers to transparency. You always know exactly what happens from the moment you contact us. We have designed a system for frictionless onboarding to make things simple for you. When you turn to us for counsel, this is what you can expect:
- Personalized intake evaluation: Founding attorney Cal Bomar still reviews intake inquiries personally. This ensures that every potential client receives a premium evaluation.
- Consultation: You will go over the details of your case with either Cal Bomar or another skilled member of our tax law team via teleconference or at an in-person meeting.
- Streamlined document transmission: No confusing paperwork chains. You will upload your financial and IRS documents through our straightforward, encrypted client portal for immediate review.
- Agree on a flat-fee structure: You will operate under a transparent, predictable flat-fee structure. This means zero surprise bills or hidden retainers. We accept payments via credit card, wire or check.
- Immediate IRS intervention: Once retained, our lawyers immediately file an IRS Power of Attorney (Form 2848), preventing the IRS from contacting you directly and routing future communications through us.
Rather than send out automated email replies, we provide detailed communication for every significant milestone of your case.
Why You Should Consult The Experienced Tax Law Attorneys At Bomar Law Firm
This new initiative gives conservation easement clients whose cases have not been added to the court’s docket a choice; continue on the path to litigation or take advantage of the IRS’s new offer. If you’ve received a settlement offer, it’s important to contact an experienced conservation easement tax law attorney before you make a decision. At Bomar Law Firm we can help review the settlement offer and help navigate next steps.
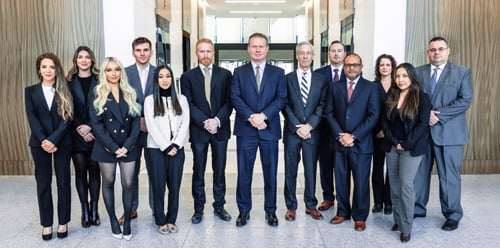
Our legal team is led by Cal Bomar, who holds an LL.M. in taxation from New York University and previously worked as tax counsel for the IRS Office of Chief Counsel in Washington, D.C. He brings an insider perspective and more than 20 years of experience to bear on tax law cases. Tax attorneys Jamie Beton and Emily Gruber focus their practice entirely on tax law concerns, including tax relief, technical cases and cryptocurrency.
Our firm is well-respected in the legal community with a long track record of success for our clients. We can evaluate the merits of the case against you, provide counsel and offer guidance on next steps. If you are already facing a lawsuit, a conservation easement attorney can help you prepare for criminal interviews and civil lawsuit tax relief associated with IRS penalties resulting from an IRS audit.
For more information on conservation easements, check out our conservation easements frequently asked questions page.

How Can You Contact Us To Obtain Relief?
To speak with a conservation easement tax attorney for a detailed analysis of how to get a positive result in your case, contact Bomar Law Firm.
The firm also handles other IRS tax matters, audits, tax relief and Tax Court litigation. Reach out for a free consultation by calling us at 404-841-6561 or sending us an email.